Kenya: Co-op Bank leads in funds set aside for absorbing defaults

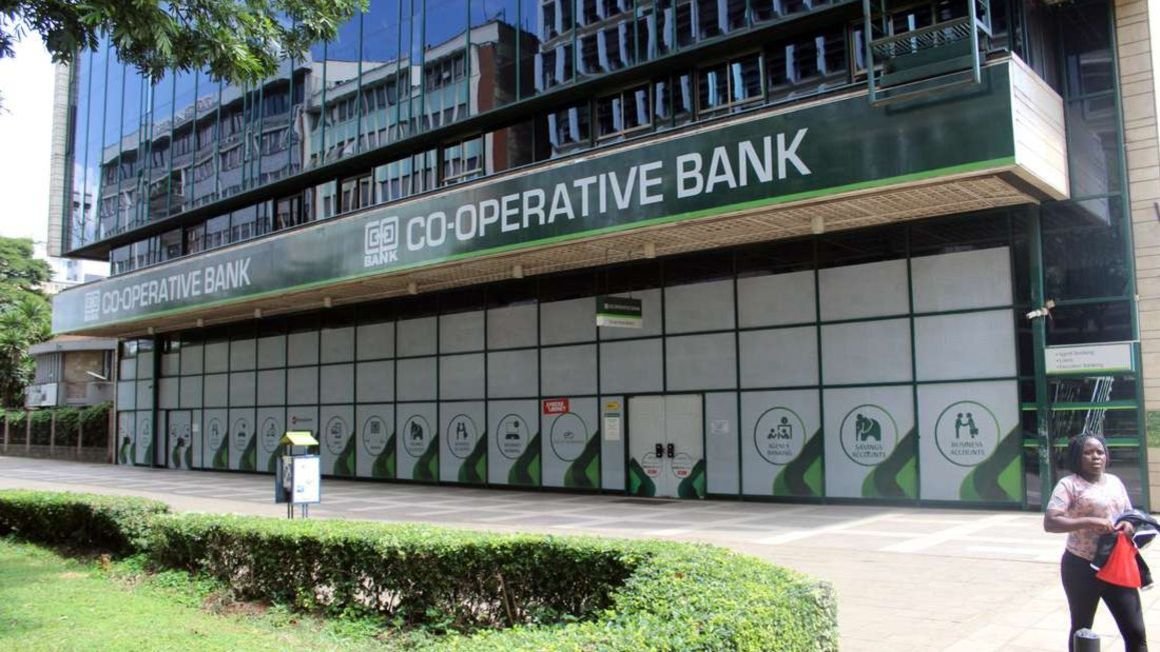
Co-op Bank has reduced its loan loss provision by the smallest margin among the big banks in the year ended December, slowing down its profit growth and leaving it with higher buffers for absorbing defaults.
Stockbroker AIB-AXYS says the lender has been the most conservative among the institutions that have released their results. Lower provisioning, a signal of increased economic optimism, has the effect of boosting earnings. Increased provisioning has the opposite effect as it raises operating expenses.
“The bank [Co-op] continues to go against the industry-wide impairment provisioning trend by reducing provisioning 2.25% year-on-year to Sh7.9 billion, significantly lower than most industry peers,” AIB-AXYS said in a brief.
The marginal reduction in provisions came as gross non-performing loans declined 15.9% to Sh49.7 billion, resulting in a loss absorption capacity of 15.8% of the bad loans.
Despite the relatively higher conservatism, Co-op Bank grew its net income 53% to Sh16.5 billion in the review period on higher interest income and lower costs.
The bank’s rivals that have published their results reduced their provisions by larger margins despite a rise in defaults, helping to lift their profits.
KCB, whose net income rose 74% to Sh34 billion, cut its provisions 52.2% to Sh12.9 billion. Its stock of bad loans meanwhile increased to Sh122.8 billion from Sh96.6 billion.
Absa Bank Kenya, whose net profit increased 161% to Sh10.8 billion, reduced its provisions 47.8% to Sh4.7 billion. Its bad loans increased to Sh19.8 billion from Sh17 billion.
Standard Chartered Bank Kenya grew its net income by two-thirds to Sh9 billion as it lowered provisions 46.3% to Sh2 billion. Its gross defaults meanwhile increased to Sh23.2 billion from Sh22.3 billion.
Banks are required to make provisions for actual and expected credit losses, with the requirement aimed at ensuring they can weather adverse economic conditions.
The level of provisions vary from one institution to another depending on the general economic conditions, specific sectors, and financial health of individual borrowers.
Some of the provisions can be reversed if financial conditions improve significantly. The banking sector in general is making big cuts in the funds it had set aside to absorb losses as the economy recovers from the impact of the Covid-19 pandemic.

Related Posts
PZ Cussons appoints Abel Idonije as new Africa People Director
Abel Idonije has been appointed Africa People Director at PZ Cussons, marking a significant new chapter in a…
 By
Leaders target financial resilience at NCBA breakfast 2026
Financial inclusion in Kenya has made significant strides, yet industry leaders gathered at the NCBA Financial Inclusion Breakfast…
Kenya Power posts KSh24.99bn as revenue climbs 8.6% in FY2026
Kenya Power and Lighting Company PLC (Kenya Power) has reported a 2.1% increase in profit after tax to…
Standard Bank Namibia, NAMCOL partner on employee value banking
The Namibia College of Open Learning (NAMCOL) and Standard Bank Namibia have strengthened their strategic partnership through a…


Gallery